You might think big money moves because of hype or charts. It doesn't. Institutions move because they can sleep at night. If a bank's legal team says "no," the billions stay in cash. That is the raw truth about regulatory impact on institutional adoption. For years, traditional finance watched the blockchain revolution from the sidelines, paralyzed by uncertainty. They didn't fear the technology; they feared the regulator. Today, that fear is turning into action, but only where the rules are clear.
Let's look at why this matters right now, in September 2026. The era of "wild west" speculation is fading for big players. What replaced it? A rigorous, often boring, process of compliance checks, custody audits, and legal opinions. When the U.S. Commodity Futures Trading Commission (CFTC) approved Bitcoin futures back in 2017, it wasn't just a product launch. It was a signal. It told institutions: "You can touch this asset without breaking your fiduciary duty." That single regulatory decision unlocked billions in capital that had been sitting idle. Now, with spot ETFs fully operational and Ethereum staking products gaining traction, we are seeing the second wave. But not all regulations are created equal. Some open doors; others slam them shut.
The Mechanics of Regulatory Clarity
What does "clarity" actually mean to a pension fund manager? It isn't vague promises. It means specific, codified rules. In Canada, for example, new federal regulations require a Regulatory Impact Analysis Statement (RIAS) a six-part document detailing description, alternatives, benefits, costs, consultation, and enforcement. This structured approach forces governments to think through the consequences before acting. For institutions, this predictability is gold. If you know the cost of compliance upfront, you can price the risk. If the rules change every six months, you can't build a long-term strategy.
The OECD has spent decades refining how governments assess these impacts. Their best practices emphasize evidence-based analysis. Why? Because bad regulation kills innovation faster than any competitor. When regulators use tools like Regulatory Impact Analysis (RIA) a systematic method to assess positive and negative effects of proposed policies, they reduce the guesswork for businesses. Institutions don't want to be test subjects. They want to operate within a framework that treats digital assets similarly to equities or bonds. Where that equivalence exists, adoption soars. Where it doesn't, capital flees to jurisdictions that get it right.
Custody: The Biggest Bottleneck
If there is one word that keeps Chief Compliance Officers awake at night, it is "custody." Who holds the keys? And what happens if they lose them? For traditional assets, this is solved. Banks hold stocks. Brokers hold bonds. But digital assets break the old models. Enter Staff Accounting Bulletin 121 (SAB121) an SEC guidance requiring entities holding crypto-assets to record associated risks on-balance sheet. Published in 2022, this rule hit hard. It forced banks to treat custodied crypto like their own liabilities, eating up precious capital reserves.
This created a massive hurdle. Many banks simply refused to offer crypto custody because the capital requirements were too high relative to the fees they could charge. Without bank-grade custody, large funds couldn't enter the market safely. They weren't going to trust a startup with cold storage when their clients' retirement savings were on the line. Recent proposals to amend the Custody Rule aim to fix this, but the delay mattered. Every month of uncertainty meant millions in potential inflows stayed out. Today, specialized custodians have filled some gaps, but the dream remains: seamless integration with existing banking infrastructure. Until SAB121 is fully resolved or repealed, expect caution from traditional banks.
The Rise of Regulated Vehicles
Institutions love wrappers. They love things they understand. You won't see many hedge funds buying raw Bitcoin on an obscure exchange anymore. They buy Exchange-Traded Products (ETPs) financial instruments traded on exchanges that track underlying assets like crypto. Why? Because ETPs come with transparency, daily liquidity, and familiar compliance frameworks. A January 2025 survey by Coinbase and EY-Parthenon confirmed this preference. Sixty percent of institutional investors prioritized ETPs and ETFs over direct holdings. That is a clear vote for regulation.
This shift has tangible market effects. When the Chicago Mercantile Exchange (CME) the world's largest derivatives exchange offering regulated Bitcoin futures launched its futures products, it legitimized Bitcoin as an asset class. Liquidity improved. Price volatility stabilized slightly. Now, with spot ETFs, we see similar dynamics. Capital flows follow the path of least resistance. In August 2025, Ethereum attracted $1.4 billion in institutional inflows, surpassing Bitcoin's $748 million during the same period. Why? Likely due to evolving narratives around utility and staking yields, but also because the regulatory pathway for Ethereum-based products became clearer. Investors aren't just chasing returns; they are chasing certainty.
Global Jurisdictions: A Tale of Two Approaches
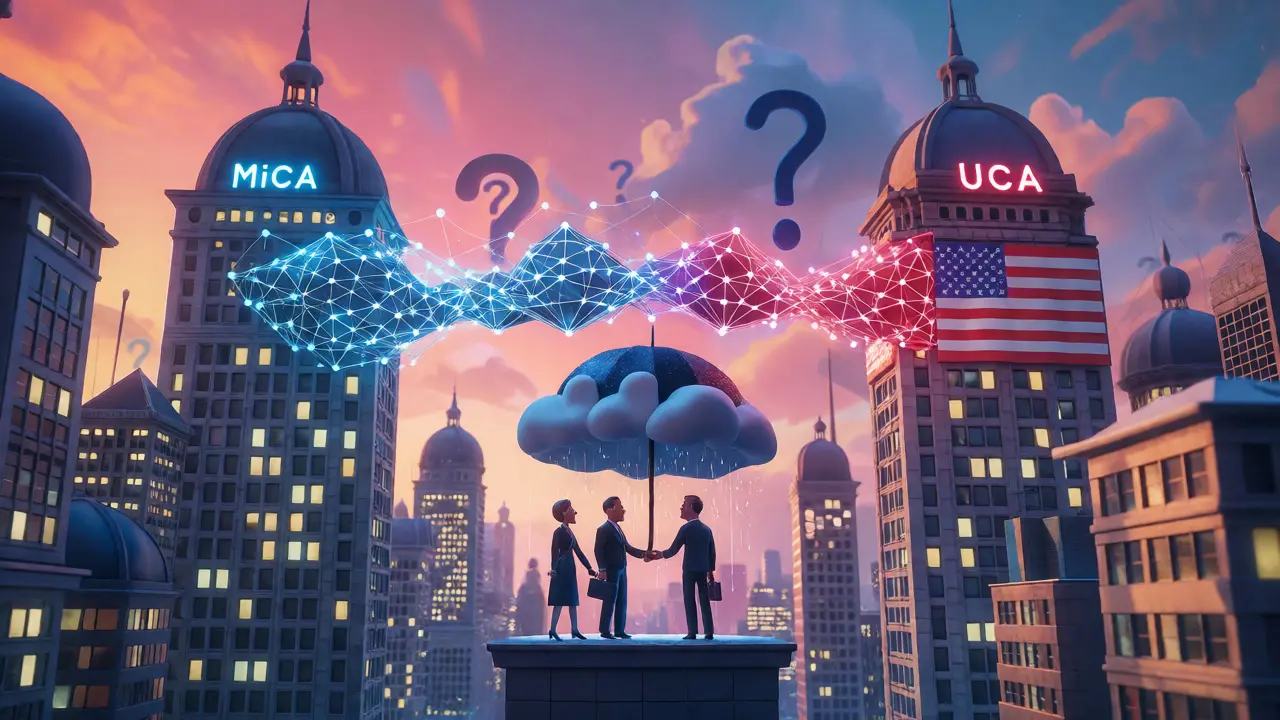
Not all countries play the same game. The European Union took a comprehensive approach with Markets in Crypto-Assets (MiCA) a EU regulation providing a unified framework for crypto asset oversight. MiCA offers a single set of rules across member states, reducing fragmentation. For a global institution, this simplicity is attractive. You can deploy capital across Europe without rewriting your compliance manual for each country.
The United States, conversely, has taken a more fragmented, agency-by-agency approach. The GENIUS Act proposed US legislation focusing on custody solutions for institutional requirements aims to address some of these gaps, particularly regarding stablecoins and custody. But until such laws pass, US institutions navigate a patchwork of state and federal rules. This asymmetry creates arbitrage opportunities but also significant risk. Firms must monitor changes in both Washington and Brussels. If the US falls behind in clarity, capital will flow to Asia or Europe. We already see signs of this with tokenized securities reaching $9.2 billion globally in early 2025, much of it driven by jurisdictions with clearer property rights definitions for digital tokens.
| Feature | EU (MiCA) | US (Current State) | Impact on Institutions |
|---|---|---|---|
| Scope | Comprehensive, cross-border | Fragmented, agency-specific | EU easier for multi-country deployment |
| Custody Rules | Standardized licensing | SAB121 constraints, pending reforms | Higher capital costs in US currently |
| Product Access | Broad range of ETPs | Spot ETFs approved, staking debated | US lagging in yield-bearing products |
| Legal Certainty | High, codified law | Moderate, reliance on case law/guidance | Lower legal risk in EU |
Tokenization: The Next Frontier
While Bitcoin and Ethereum grab headlines, the real institutional interest lies in tokenized securities digital representations of ownership in traditional assets like real estate or private equity. This is where regulation meets efficiency. Traditional private equity deals take weeks to settle. Tokenized versions can settle in seconds. But who owns the token? Does it represent equity? Debt? Revenue share? These questions need legal answers before big pensions jump in.
We saw tokenized assets gain traction in early 2025, particularly in real estate and private credit. Institutions like these because they offer diversification away from public markets. However, they demand ironclad smart contract audits and clear legal recourse. If a smart contract bug drains the pool, is it negligence? Fraud? Code error? Regulation defines liability. Without it, institutions won't touch it. The rise of compliant platforms suggests progress, but the pace depends on courts and legislatures catching up to code.
Risk Management in a Shifting Landscape
Don't mistake regulatory clarity for safety. Sudden shifts still cause volatility. Remember when China banned mining? Prices dropped instantly. Or when the SEC sued major exchanges? Uncertainty spiked. Institutions mitigate this by diversifying jurisdictions. They keep assets in multiple custody providers across different legal systems. They also stress-test their portfolios against regulatory shocks. What if KYC-AML (Know Your Customer-Anti Money Laundering) rules tighten overnight? Can your provider adapt?
Fidelity Digital Assets noted that asymmetric regulation historically prevented deeper involvement. Now, as frameworks mature, the focus shifts to operational resilience. Institutions are building teams that include not just traders, but lawyers and compliance officers who speak fluent blockchain. This cultural shift is profound. It signals that digital assets are no longer a side bet; they are core portfolio components requiring serious governance.
Key Takeaways
- Clarity drives capital: Institutions prioritize regulated vehicles like ETFs and ETPs over direct holdings to minimize legal risk.
- Custody is critical: Regulations like SAB121 significantly impact banks' willingness to hold digital assets, affecting overall market access.
- Global divergence matters: Differences between EU's MiCA and US frameworks influence where institutions allocate resources.
- Tokenization needs legal backing: Real-world asset adoption depends on clear property rights and liability definitions for digital tokens.
- Compliance is a feature: Robust KYC-AML procedures are now seen as selling points for institutional-grade platforms, not just burdens.
Why do institutions prefer ETFs over direct cryptocurrency holdings?
Institutions prefer Exchange-Traded Products (ETPs) and ETFs because they operate within familiar regulatory frameworks. These products offer transparency, daily liquidity, and established investor protections, which simplify compliance and reduce legal risks compared to managing direct custody of volatile digital assets.
How does SAB121 affect banks wanting to offer crypto custody?
Staff Accounting Bulletin 121 requires SEC reporting entities holding crypto-assets to record the associated risks on their balance sheets. This treatment increases capital requirements for banks, making it more expensive to offer custody services, which has historically discouraged many traditional financial institutions from entering the space.
What is the difference between MiCA and US crypto regulations?
The EU's Markets in Crypto-Assets (MiCA) regulation provides a comprehensive, unified legal framework across all member states. In contrast, the US relies on a fragmented approach involving multiple agencies like the SEC and CFTC, leading to less consistency and higher compliance complexity for firms operating nationally.
How does regulatory clarity impact market liquidity?
Clear regulations encourage institutional participation, which brings substantial capital into the market. This increased volume improves liquidity, tightens bid-ask spreads, and generally reduces extreme price volatility, making the asset class more attractive to other risk-averse investors.
Are tokenized securities considered safe for institutional investors?
Safety depends on the jurisdiction and the specific legal structure of the token. Institutions require clear definitions of ownership rights, enforceable smart contracts, and reliable custodial solutions. As regulations evolve to define these parameters, tokenized securities become increasingly viable for conservative portfolios.
Comments
Clarity? Please. It's just a mechanism for the state to assert total dominion over every transaction, every wallet, every satoshi!!! The 'clarity' you speak of is merely the illusion of permission granted by those who fear losing control!!! They don't want institutions to adopt; they want institutions to police!!! SAB121 wasn't a mistake; it was a feature designed to bleed retail capital dry while big banks wait in the wings!!! Don't be fooled by the shiny ETF wrappers!!! They are Trojan horses carrying surveillance into your portfolio!!!
I appreciate the dramatic flair, but from a compliance perspective, the uncertainty prior to clear guidelines was genuinely paralyzing for fiduciary duties.
When legal teams cannot define liability, they default to avoidance. That isn't conspiracy; it's risk management.
The shift toward ETPs reflects a desire for standardized reporting that integrates with existing GAAP frameworks.
The premise is flawed. Institutions do not move because they can sleep at night; they move because the profit motive overrides their anxiety. Your analysis ignores the sheer greed driving these decisions. The regulatory framework is secondary to the arbitrage opportunity presented by institutional inflows. One must recognize that clarity is often manufactured to serve specific interests rather than public good.
It is morally imperative that we prioritize safety and stability over reckless speculation! 😊
We have seen too many families lose their savings to unregulated chaos. 🙏
Regulation protects the vulnerable from the predatory practices of early adopters. 💪
Institutions bringing discipline to this space is a victory for ethical finance. ✨
They are coordinating globally to trap us all. 😟
MiCA in Europe and the patchwork in the US are two sides of the same coin. 🪙
The delay in SAB121 repeal was intentional to protect legacy banking fees. 💸
Do not trust the 'clarity'. It is a cage. 🔒
The fragmentation of the US regulatory landscape creates a fascinating asymmetry in market dynamics.
While MiCA offers a unified front, the US approach fosters a competitive environment among agencies like the SEC and CFTC.
This jurisdictional arbitrage allows sophisticated players to optimize their compliance costs across borders.
However, the lack of federal uniformity remains a significant drag on broader institutional participation compared to European counterparts.
The tokenization sector, in particular, suffers from this ambiguity regarding property rights definitions.
Until the GENIUS Act or similar legislation passes, US institutions will continue to hedge their bets by diversifying custody solutions internationally.
The operational resilience required to navigate this complexity is non-trivial and resource-intensive.
Ultimately, the market will force convergence, but the path will be littered with stranded assets and failed pilots.
We are witnessing a structural evolution, not just a cyclical trend.
The interplay between technology and law is defining the next decade of financial infrastructure.
honestly this whole thing feels like gatekeeping again
they add rules so only the rich can play safely
retail gets left holding the bag while banks figure out custody
its always about protecting the incumbents
the tech works fine without them
regulations just slow down adoption for everyone else
we dont need their permission to use code
but sure lets pretend its about 'sleeping at night'
its about control
always has been
You're missing the point entirely. Banks aren't scared of regulators; they're scared of losing their monopoly on money creation. Digital assets threaten their business model directly. That's why they lobby for strict custody rules-to keep the competition out. Simple as that. No one cares about 'sleeping at night.' They care about quarterly earnings. Stop romanticizing the process.
It’s understandable to feel frustrated by the pace of change, especially when the potential for efficiency gains is so high.
However, viewing regulation solely as a barrier might overlook the foundational work being done to create sustainable ecosystems.
For many smaller funds, the clarity provided by frameworks like MiCA actually lowers the barrier to entry by standardizing expectations.
We should strive to see these developments as collaborative efforts between technologists and policymakers to build something durable.
Empathy for the cautious approach helps us understand why large pensions move slowly-they have a duty to beneficiaries that demands prudence.
Let’s focus on how we can bridge the gap between innovation and governance constructively.
From an international perspective, the divergence between EU and US approaches highlights different cultural attitudes toward risk and privacy.
Europe tends to prioritize consumer protection and systemic stability through comprehensive legislation.
The United States often favors market-driven solutions with reactive regulatory adjustments.
Both models have merits, but global institutions must adapt to this duality.
Understanding these nuances is crucial for anyone operating in cross-border digital asset markets.
The reliance on case law in the US is inefficient. Period.
Finally, some sense! While I hate the bureaucratic red tape, seeing American institutions lead the charge in regulated vehicles proves our financial system still has teeth. We shouldn't let other jurisdictions dictate our standards. If MiCA is simpler, fine, but the depth of the US market is unmatched. Let's keep pushing for domestic clarity so we don't export our jobs to Brussels or Singapore. This is America's playground, and we're finally setting up the fences properly.
Love this breakdown! 🚀 It really helps demystify why big money moves the way it does.
Seeing the shift to ETPs makes total sense for folks who want exposure without the headache of private keys. 🔑
Compliance isn't boring; it's the bridge to mainstream acceptance! 🌉
Keep spreading the word that safe investing is possible now! 💡
Great post! It’s helpful to remember that for many investors, the 'boring' stuff like custody audits is what allows them to participate confidently.
If you’re new to this space, starting with regulated products is a solid step before diving into direct holdings.
Supportive advice: take your time understanding the custodial risks.
Everyone learns at their own pace, and there’s no shame in preferring the safety net of an ETF.
Keep exploring!
We have a moral obligation to ensure that financial systems serve society, not just enrich speculators. Regulation provides the guardrails necessary for this purpose. Without it, we revert to the wild west where the powerful exploit the weak. Institutional adoption, guided by clear laws, represents a maturation of the industry towards ethical responsibility.